RESCISSION CALENDAR
Right of rescission calendar: counting the three business days
Saturdays count. Sundays do not, and neither do the federal holidays the statute names. Miss one of those on a holiday week and your date is a day out. Below is how the count runs, worked through the July 2026 weekend, where it goes wrong most often.
Back to NotaryLog →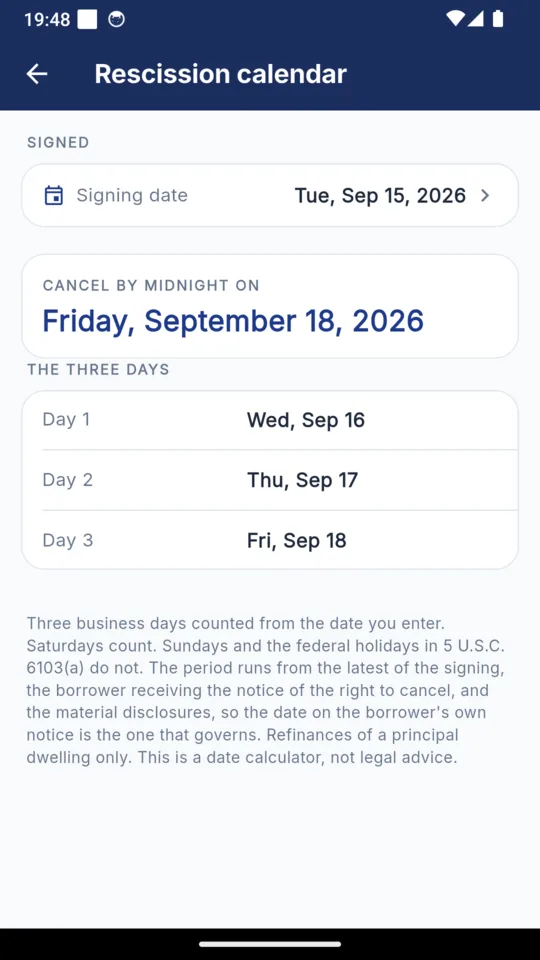
The rule in one paragraph
On a consumer loan secured by the borrower’s principal dwelling that was not used to buy or build it, the borrower may cancel until midnight of the third business day after the last of three events. Regulation Z sets it out at 12 CFR 1026.23, and the definition of a business day that applies to it sits at 12 CFR 1026.2(a)(6). Everything that follows here comes out of those two paragraphs.
The clock starts at the latest of these three
- Consummation. The moment the borrower becomes contractually obliged, which on a table-funded signing is usually the signing itself.
- The notice of the right to cancel. Each borrower with the right has to receive it, and there are normally two copies each.
- The material disclosures. The federal disclosures the rule names, delivered to the borrower.
The signing date is the start only when it is the last of the three. If a disclosure lands late, the period starts late, and the date printed on the borrower’s own notice is the one that governs. A calendar cannot see any of that, which is why this one asks for a date rather than trying to guess which event was last.
What counts as a business day here
Regulation Z carries two definitions of business day, and rescission uses the wider one: every calendar day except Sundays and the legal public holidays listed in 5 U.S.C. 6103(a). It is not the lender’s opening hours, and it is not weekdays only.
So Saturday is an ordinary counted day, and that is where most wrong dates come from. A Thursday signing with no holiday in the way counts Friday, Saturday and Monday. The right ends on the Monday at midnight, not the Tuesday.
| Holiday | When it falls |
|---|---|
| New Year’s Day | January 1 |
| Birthday of Martin Luther King, Jr. | Third Monday in January |
| Washington’s Birthday | Third Monday in February |
| Memorial Day | Last Monday in May |
| Juneteenth National Independence Day | June 19 |
| Independence Day | July 4 |
| Labor Day | First Monday in September |
| Columbus Day | Second Monday in October |
| Veterans Day | November 11 |
| Thanksgiving Day | Fourth Thursday in November |
| Christmas Day | December 25 |
The observed day is the part people trip on. The statute names four of these by date. When one of those lands on a weekend, federal offices close on the neighbouring weekday instead, and that observed day is not one of the named dates.
So NotaryLog skips the named date and counts the observed weekday. A day is not excluded merely because federal offices are shut on it. The lender still sets the dates the loan runs on, so when a holiday weekend falls near the window, check the date against the borrower’s notice.
A worked example: signing on Thursday 2 July 2026
Independence Day 2026 is a Saturday, which makes that week the clearest case of the year. Federal offices take Friday 3 July off. The statute still names 4 July.
| Date | Counts as | Why |
|---|---|---|
| Thu, Jul 2 | Signing | The count starts the day after, not on the day itself |
| Fri, Jul 3 | Day 1 | Counted. Federal offices observe Independence Day today, but the statute names July 4 |
| Sat, Jul 4 | Skipped | Independence Day, a named holiday |
| Sun, Jul 5 | Skipped | Sunday |
| Mon, Jul 6 | Day 2 | Counted |
| Tue, Jul 7 | Day 3 | The right to cancel ends at midnight |
The right to cancel ends at midnight on Tuesday 7 July 2026. Count the observed Friday as a holiday instead and you land on Wednesday, a day late. Forget that Saturday counts and you land on Thursday, two days late.
What the app does with it
Open the rescission calendar from a job or on its own and give it the date the period runs from. It shows the date the borrower can cancel until, the three days it counted, and every day it skipped with the reason written beside it. Read that skipped list. It is what lets you check the answer rather than take it.
It is part of the Business tier, alongside jobs, invoices, mileage and expenses. The journal itself, which is the record of the notarial act, is the other half of the app and works on its own.
What the screen tells you, verbatim: three business days counted from the date you enter, Saturdays count, Sundays and the federal holidays in 5 U.S.C. 6103(a) do not. The period runs from the latest of the signing, the borrower receiving the notice of the right to cancel, and the material disclosures, so the date on the borrower’s own notice is the one that governs. Refinances of a principal dwelling only. This is a date calculator, not legal advice.
Questions
The ones that decide the date.
Does Saturday count as a business day for rescission?
Yes. For rescission, Regulation Z uses a wider definition than the one it uses elsewhere: every calendar day except Sundays and the legal public holidays listed in 5 U.S.C. 6103(a). Saturday is an ordinary counted day, which is why a Thursday signing so often ends on a Monday.
When does the three days start?
The day after the latest of three things: the loan is consummated, the borrower receives the notice of the right to cancel, and the borrower receives all the material disclosures. The signing date is only the start when it is the last of the three, so the date on the borrower’s own notice is the one that governs.
What time does the right to cancel end?
Midnight at the end of the third counted day. Funding usually follows after that, and the lender decides when it disburses, so confirm the date with them rather than with a calculator.
Which signings carry a right of rescission?
Broadly, consumer credit secured by the borrower’s principal dwelling that was not used to buy or build it, which in practice means refinances, home equity loans and HELOCs. A purchase money mortgage does not carry it, nor does a loan on a second home or an investment property, and a refinance with the same creditor on the same property is excluded except for any new money.
What about a holiday that falls on a weekend?
5 U.S.C. 6103(a) names the holidays by date. When one lands on a weekend, federal offices close on the neighbouring weekday instead, but that observed day is not one of the named dates. NotaryLog therefore skips the named date and counts the observed weekday, because a day is not excluded merely because federal offices are shut on it. The dates on the borrower’s notice are still the ones the loan runs on.
Is the notary responsible for this date?
The lender sets the period and the notice states the dates, so follow the documents and the closing instructions rather than a calculator. A signing agent works the date out to know when the package is clear and when to expect the next one, which is the job this calendar does.
This page is general information about how a date is counted, not legal advice, and nothing here is a statement about your loan. Rescission rights, the disclosures that start the period and the treatment of an observed holiday are questions for the lender and, where it matters, an attorney. NotaryLog works out a date from the one you give it; it does not decide whether a right to cancel exists or when it ends.
Keep reading
GUIDE
Notary journal requirements
Why the journal exists, what a complete entry generally contains, the mistakes that cause trouble later, and how long to keep it.
GUIDE
Notary journal template
The full field list with what belongs in each one, the standard act and ID options, and one entry filled in end to end.
THE APP
NotaryLog
The offline journal itself, plus the jobs, invoices, mileage and expenses that make up the Business tier.
Work the date out at the table
The calendar, the job, the invoice and the journal entry on one phone, offline, with no account. Business is $7.99 a month or $59.99 a year, and it carries the journal tier with it.